Lead Prediction§2 Compliance
§2

Compliance and regulatory position

Lead Prediction is a marketing services company. We are not a lender, not a broker, and not an originator. This section sets out the regulatory framework we operate inside and the division of responsibility between us and your firm.

What compliant creative looks like

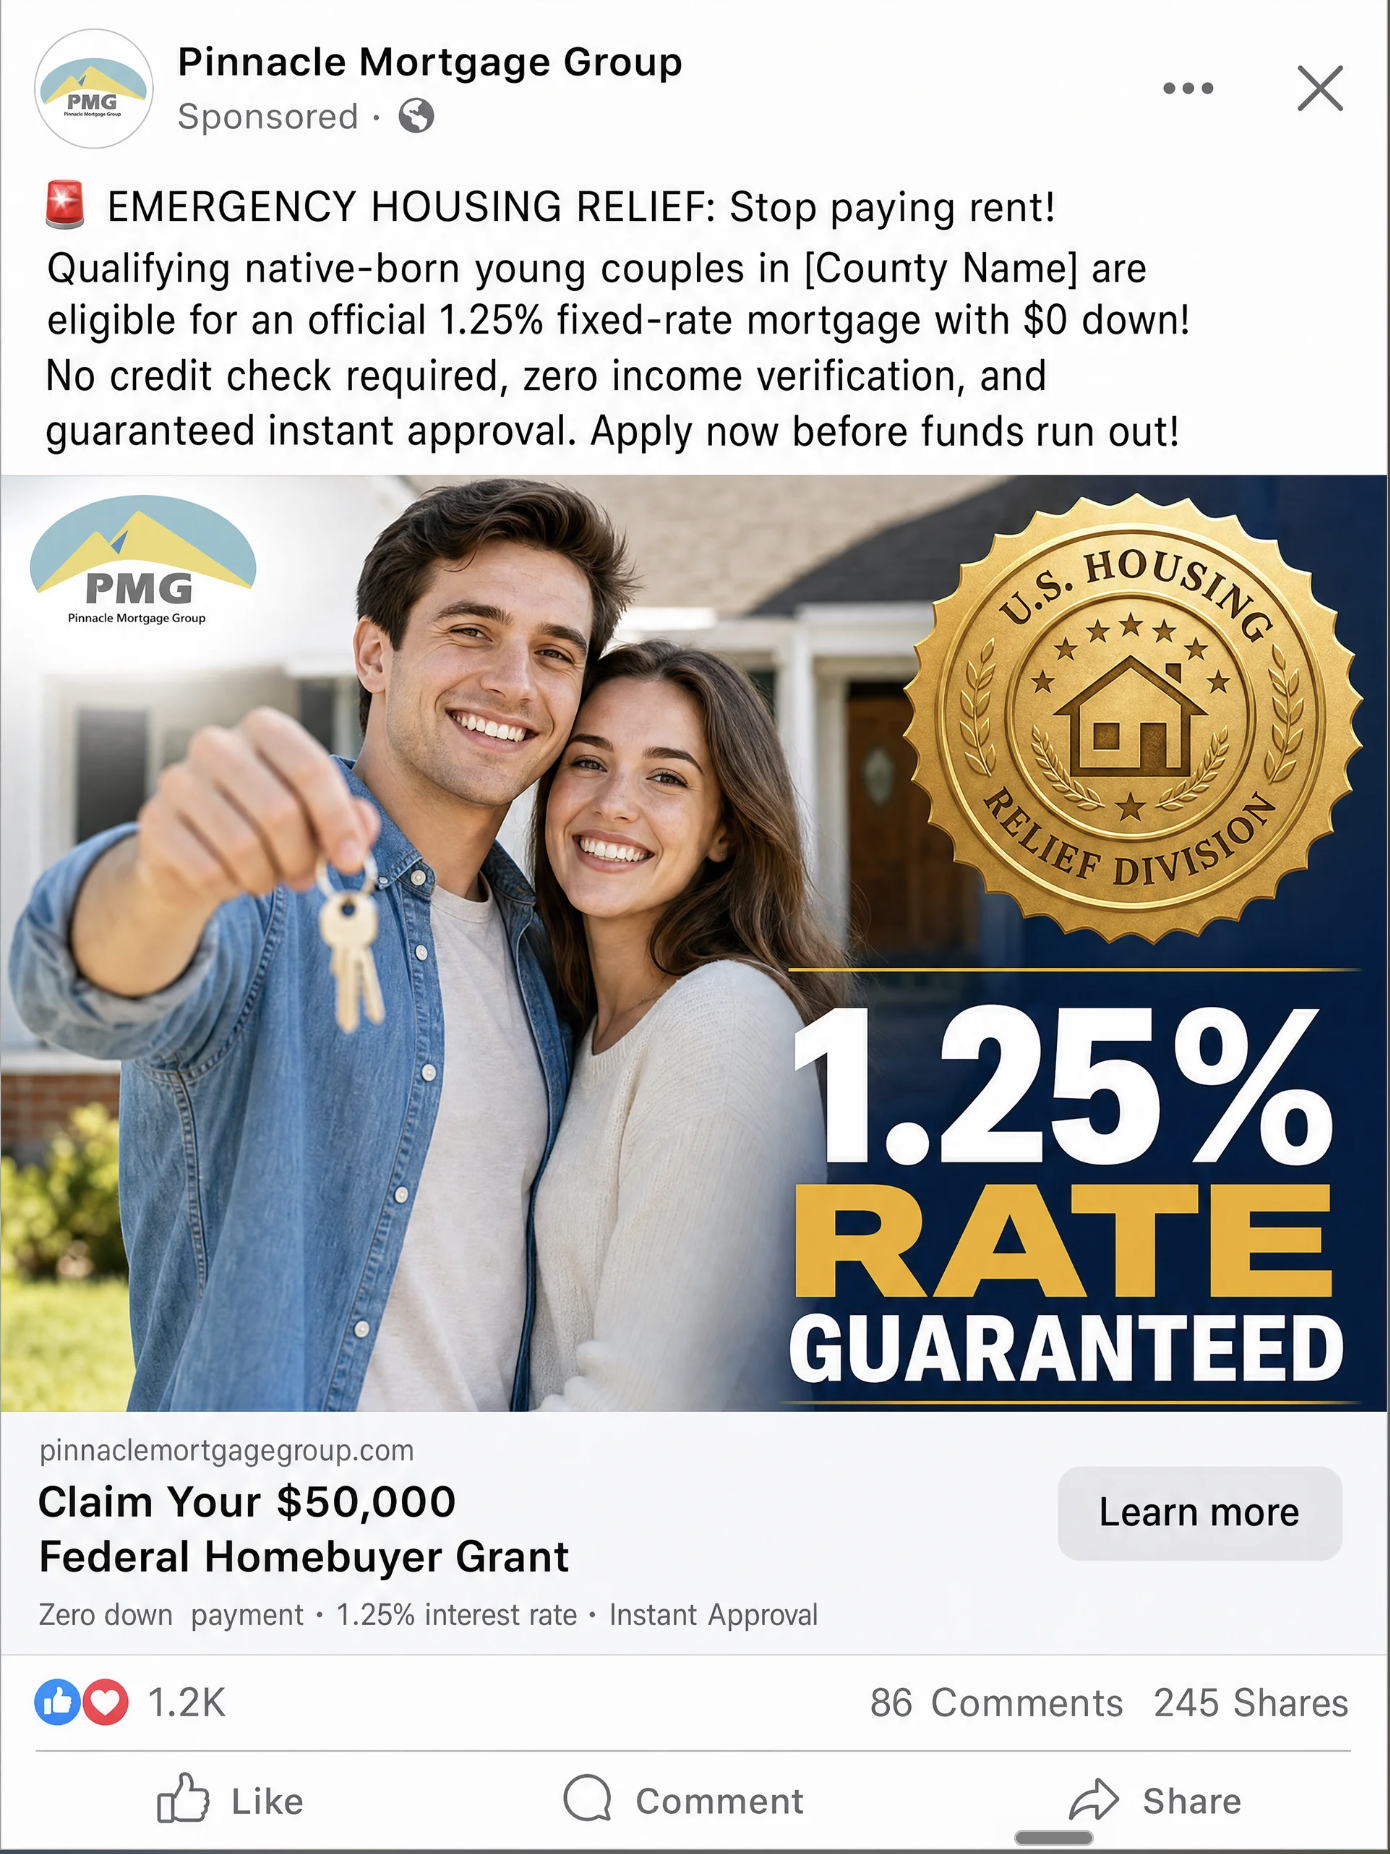
Typical mortgage adNon-compliant
Screenshot of a non-compliant mortgage ad quoting a 1.25% guaranteed rate, with no NMLS identifier and no Equal Housing marking

Image · 02-AD-FAIL — a live non-compliant ad: triggering terms, approval claims, and missing disclosures.

  • Rate quoted in the headline — a triggering term under Regulation Z with no accompanying disclosure
  • "Guaranteed approval" — an approval claim we will not publish
  • No NMLS identifier anywhere on the asset
  • No Equal Housing marking
  • Targeting set by ZIP code and age — unavailable under the Special Ad Category
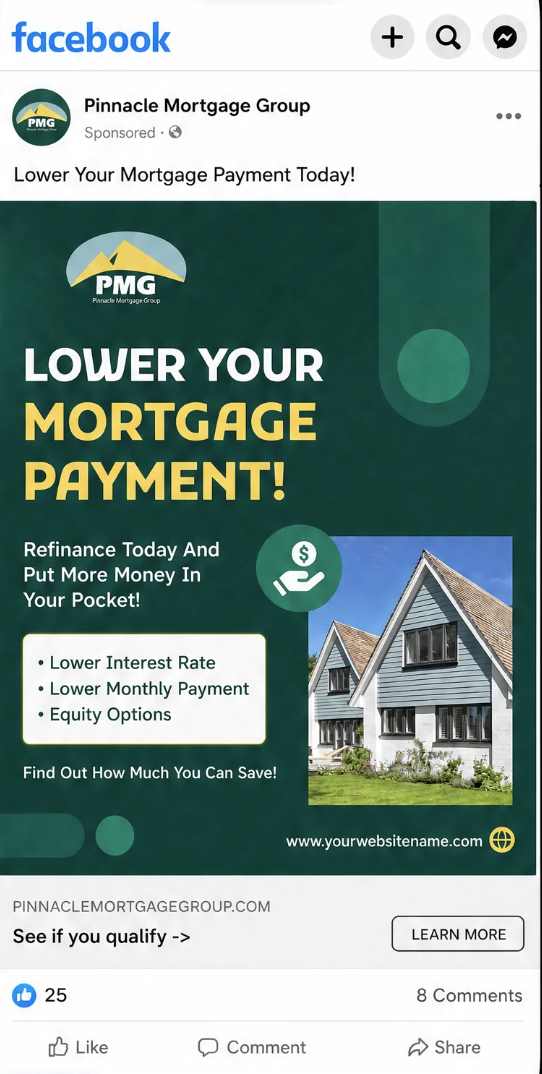
Ad we would runCompliant
Mockup of a compliant mortgage ad with no triggering terms, including NMLS identifier and Equal Housing marking

Image · 02-AD-PASS — the same offer rewritten to stay inside the compliance lines.

  • No rate, payment, term or down payment figure anywhere in the creative
  • Firm NMLS identifier present on the asset
  • Equal Housing marking present
  • Benefit and situation led copy, no outcome claim
  • Runs inside the Special Ad Category for Credit and Housing
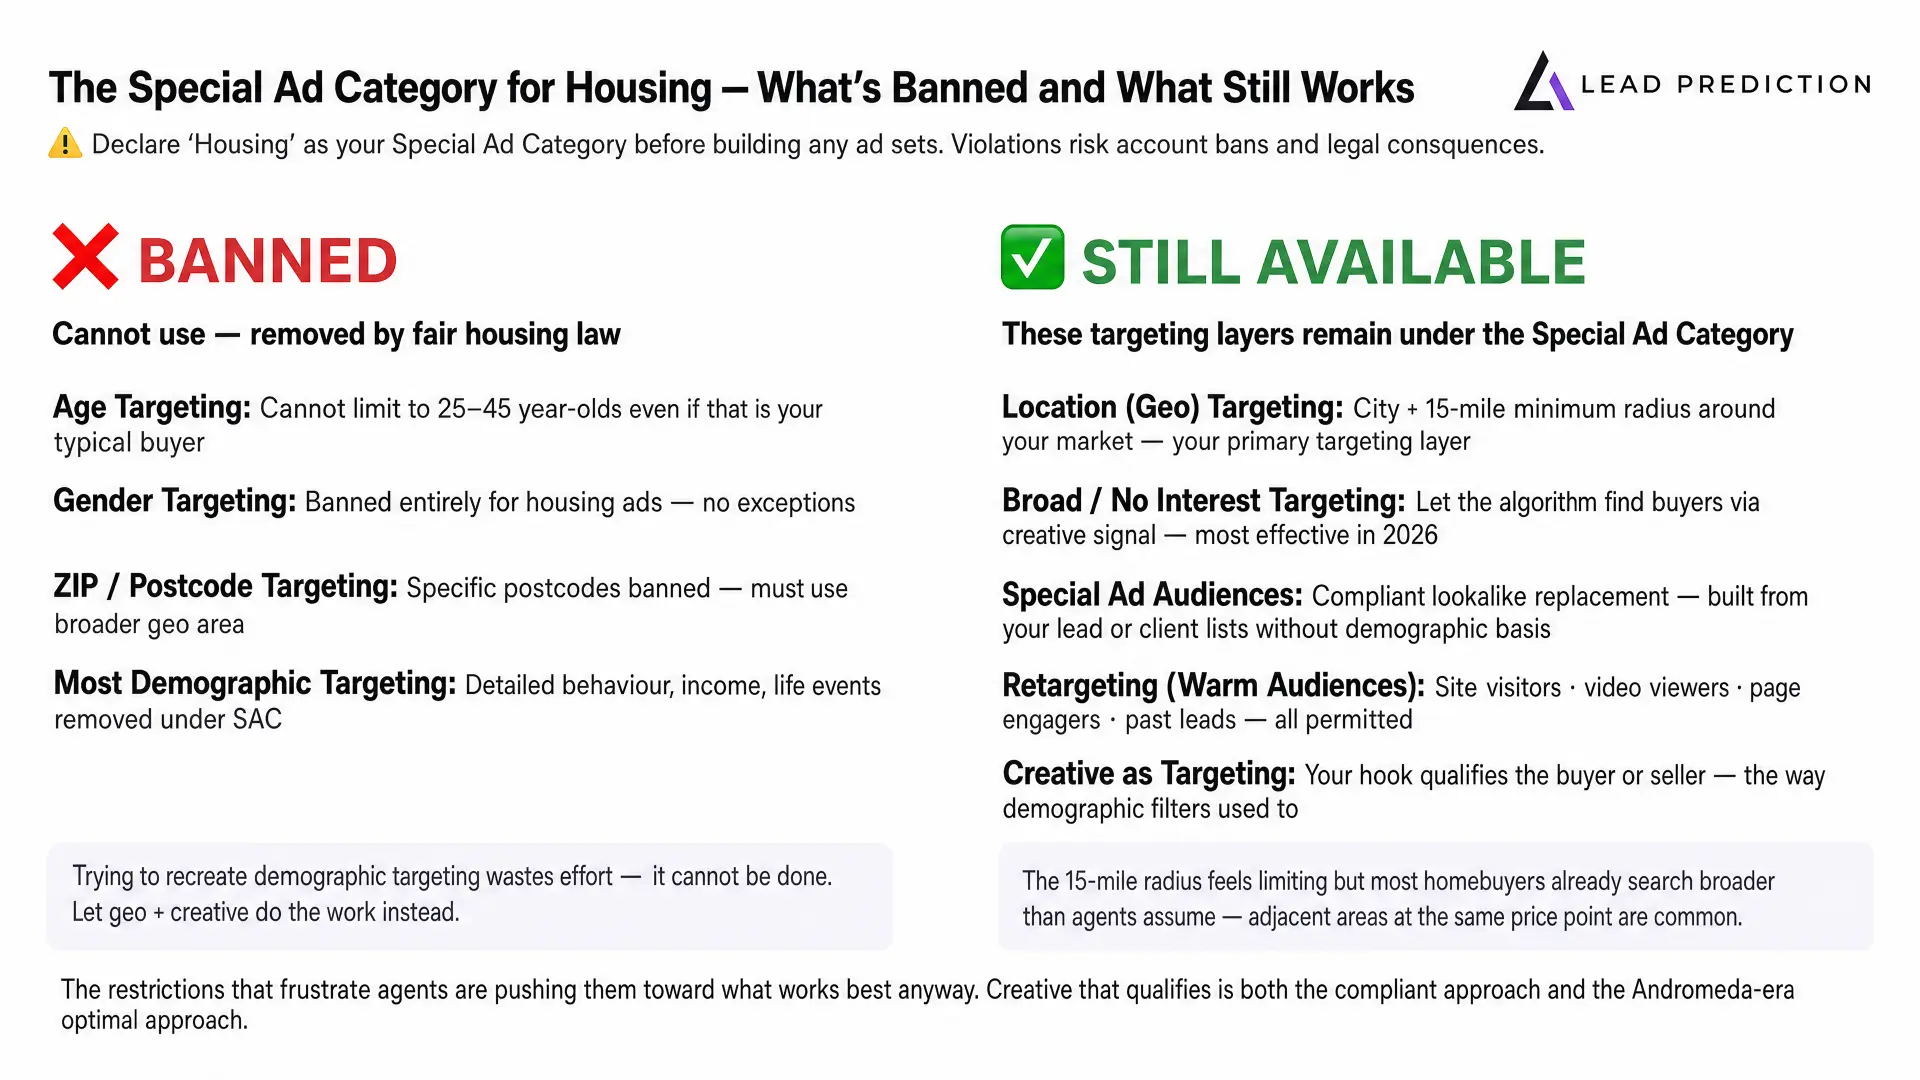
Special Ad Category for Housing: banned targeting options versus compliant targeting options still available
Screenshot · 02-META-TARGETING — what is banned and what still works under the Special Ad Category for Housing.

The framework

RESPA — Section 8

We are paid a flat monthly retainer for marketing services rendered. We are never paid per lead, per appointment, per application, or as any share of a funded loan. Section 8 prohibits fees for the referral of settlement service business, and a per-lead compensation structure risks being construed exactly that way. Our structure removes the question.

Regulation Z — triggering terms

No specific interest rate, monthly payment, down payment amount, or term appears in any creative we produce. Stating a triggering term obliges full disclosure of all material terms including APR. Our creative is written to benefit and situation, not to numbers.

Fair Housing and ECOA

All campaigns run under Meta's Special Ad Category for Credit and Housing. That removes age, gender, ZIP-code and detailed-interest targeting, and standard lookalike audiences. We treat those restrictions as a design constraint and build qualification into the form and the creative instead of the targeting.

Licensing and NMLS

Your firm's NMLS identifier and Equal Housing marking appear on every asset we produce. Producer-level identifiers are captured at onboarding. Borrowers from states in which you are not licensed are filtered before they reach a producer.

TCPA and consent

Consent language is presented at the point of submission, and IP address, timestamp and form contents are retained as the consent record. SMS traffic runs on registered A2P 10DLC infrastructure. Consent language is reviewed by counsel and re-reviewed if your licensed-state footprint, script, retry cadence, or routing changes.

FTC and MAP Rule

We do not publish approval claims, rate guarantees, or projected loan outcomes in any creative. Every claim made in advertising has a documented basis on file.

Approval control

Every ad, every piece of copy, and every form question is presented to you for written approval before it runs. Nothing you have not seen is published.
Division of responsibility

ResponsibilityHeld by
Origination licensing and state registrationsYour firm
NMLS identifiers and disclosure requirements specific to your statesYour firm
Loan terms, product eligibility, and all borrower adviceYour firm
Final approval of all advertising before publicationYour firm
Regulatory compliance of your origination processYour firm
Advertising creative built to the constraints aboveLead Prediction
Special Ad Category configuration and campaign operationLead Prediction
Consent capture, consent records, and A2P registrationLead Prediction
State-licence routing configurationLead Prediction
Retention of substantiation for claims made in creativeLead Prediction

What we do not do

  • Originate loans
  • Advise borrowers on products, terms or eligibility
  • Quote or discuss rates
  • Provide legal or compliance advice to your firm
  • Take custody of your ad spend
  • Own or hold your borrower data